 VA loan funnel
A VA loan funnel built with respect and clear next steps
Veterans hear a lot of noise about "zero down". This funnel cuts through it: a few plain questions, a clear explanation of what the Certificate of Eligibility is, and a real person on the phone.
Included in every plan · or add to any plan for $59/mo
Question 1 of 4
What best describes your service?
Question 2 of 4
What are you planning?
Question 3 of 4
When do you need to move?
What it is
What is a va loan funnel?
A VA loan funnel is a landing page and short quiz for veterans and service members that asks about service status, timeline and home goals, explains eligibility next steps such as the Certificate of Eligibility, and books a call with a loan officer who handles VA loans — without implying the LO is part of the VA.
Who it's for
Veterans, active-duty service members, National Guard and Reserve members, and some surviving spouses who may be eligible for a VA-guaranteed loan. Many are relocating on orders and on tight timelines.
What makes them search
- PCS orders or relocation
- Separation from service
- Growing family
- Rent near base rising
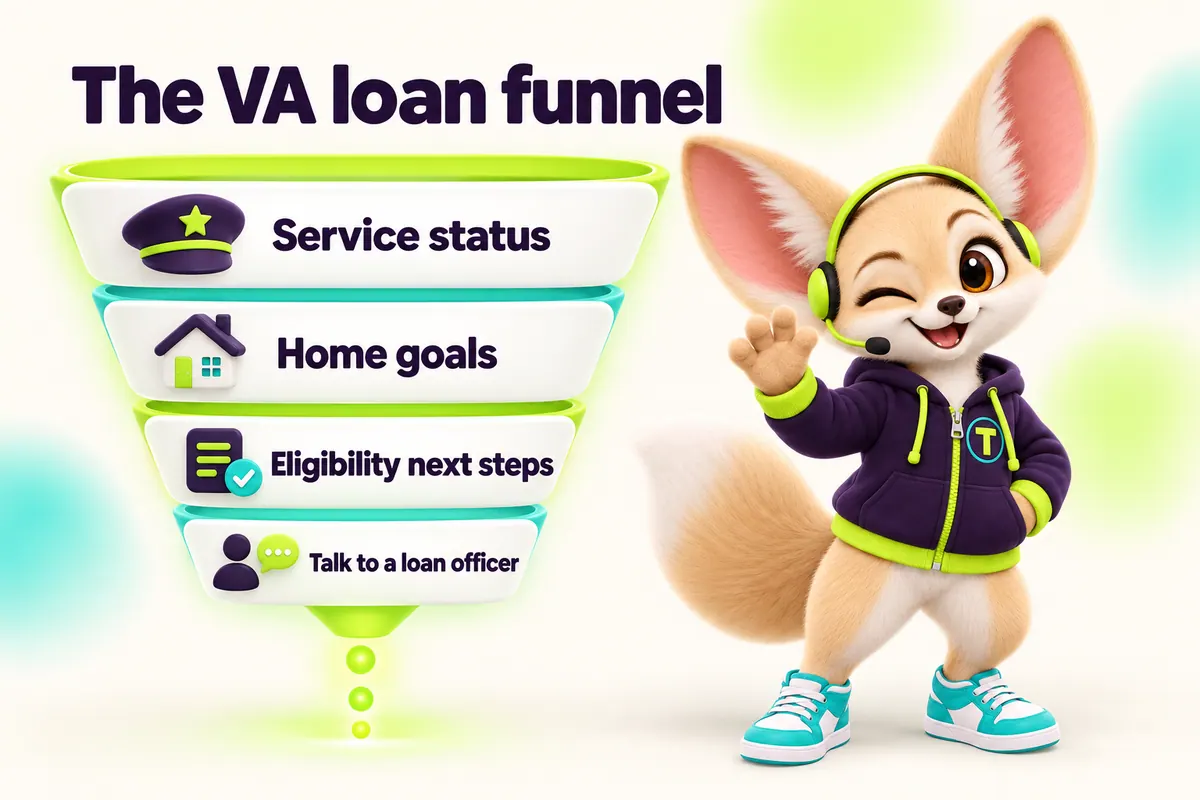
The funnel map
How the VA loan funnel moves a borrower
- 01
Ad or link
Ad angle 1 of 3
Using your VA home loan benefit? Start with 3 questions
- 02
Landing page
One screen, one promise
A VA loan funnel is a landing page and short quiz for veterans and service members that asks about service status, timeline and home goals, explains eligibility next steps such as the Certificate of Eligibility, and books a call with a loan officer who handles VA loans — without implying the LO is part of the VA..
- 03
4-question quiz
Tap-only answers
What best describes your service? · What are you planning? · When do you need to move? · Have you used your VA loan benefit before?
- 04
Result page
Next step, no promises
The result page explains eligibility and entitlement in plain words, lists what a Certificate of Eligibility is and how the LO can help request it, and offers a call — never a promise of approval or a "no money down" guarantee.
- 05
Handoff & follow-up
5 touches written for you
Service status and timeline carry into the application and the CRM so the LO starts the call already knowing the PCS date.
The questions, word for word
Four taps. No paperwork yet.
This is the quiz we write for you (your edits welcome). Every answer is a button, so it works one-handed on a phone.
Question 1
What best describes your service?
- Veteran
- Active duty
- Guard or Reserve
- Surviving spouse
Question 2
What are you planning?
- Buy a home
- Refinance a VA loan
- Cash-out refinance
- Not sure yet
Question 3
When do you need to move?
- Within 60 days
- 2–6 months
- Later this year
- No set date
Question 4
Have you used your VA loan benefit before?
- No, first time
- Yes, once
- Yes, and I still own that home
- Not sure
Result page
What the borrower sees next
The result page explains eligibility and entitlement in plain words, lists what a Certificate of Eligibility is and how the LO can help request it, and offers a call — never a promise of approval or a "no money down" guarantee.
Follow-up, written for you
What happens after they tap "done"
The follow-up below runs from the CRM included with your site. Texts only go to borrowers who ticked the SMS consent box. Messages are sample copy — we tailor them to your voice.
- 0–30 secondsSMS
Thank you for your service, {first}. I'm {LO} and I help with VA home loans. Want to talk through your move timeline? {calendar} Reply STOP to opt out.
- 5 minutesEmail
"Your VA loan next steps" — COE explained, documents to gather (DD-214 or statement of service), booking link.
- 30 minutes (no booking)Call
LO call attempt with the quiz answers on screen.
- Day 3SMS
Checking in — is your move date still {timeline}? Happy to plan around it.
- Day 10Email
"VA funding fee: what it is and who is exempt" — general education with a link to the VA's own page.
Ads & compliance
Ad angles that work — and stay compliant
Sample ad angle
"Using your VA home loan benefit? Start with 3 questions"
Benefit framing, no "$0 down" claim without the required context.
Sample ad angle
"Moving on orders? Plan your home purchase early"
Timeline angle for PCS moves; no base names or insignia in creative.
Sample ad angle
"What the Certificate of Eligibility is — and how to get it"
Educational hook; links to a calm explainer.
Compliance built in
- No VA seal, insignia, or wording that suggests the LO is the VA or a government agency (Regulation N prohibits misrepresenting government affiliation).
- "No down payment" only with the conditions that make it accurate, reviewed by the LO's compliance team.
- NMLS ID and Equal Housing Opportunity on every page.
- Military status is used only to tailor information, never to target ads by protected traits.
We explain public rules; we don't give legal advice. Your compliance team approves every funnel before launch. Mortgage ad compliance, explained.
What we watch
Numbers that tell us it's working
- 1Booked-call rate within 24 hours
- 2Share of leads with a move date under 60 days
- 3Application starts
- 4Reply rate to the first text
On Funnel Stack and Full Library we test one or two changes a month (a headline, a question order) and report what moved.
Included with this funnel
- Landing page, 4-question quiz and result page, written and built
- Application handoff, pre-filled from the quiz
- 5-touch follow-up in the CRM (SMS with consent, email, tasks)
- 3 ad angles written to avoid unbalanced trigger terms
- Schema, FAQs and your NMLS / Equal Housing block on every page
Not included
- Ad spend (paid to Meta or Google from your account)
- Legal or compliance approval (your compliance team)
- Loan decisions — those stay with you
FAQ
VA loan funnel questions
Specific to the va loan funnel. General questions live on the FAQ page.
Can't find it? Search every answer or ask the funnel desk.
Can we say "VA approved" on the funnel?
Be careful. The VA guarantees loans; it does not endorse loan officers. Wording that suggests your company is the VA or acts for the government can mislead and is prohibited by Regulation N. We write "VA home loans" and "we help you use your VA benefit" instead, and your compliance team signs off.
Do VA loans really need no down payment?
For eligible borrowers with full entitlement, the VA does not require a down payment on many purchases, but lenders set their own requirements and other costs still apply. Because the statement depends on conditions, the funnel explains it carefully on the result page rather than shouting it in an ad.
What is a Certificate of Eligibility?
The Certificate of Eligibility (COE) is the VA document that shows a lender the borrower qualifies for the VA home loan benefit and how much entitlement they have. Lenders can often request it electronically; the funnel explains this so the borrower is not stuck.
Can the funnel handle VA refinances too?
Yes. The second quiz question branches: purchase, VA-to-VA refinance, or cash-out. Each branch gets its own result page and follow-up so a refinance lead is not sent home-buying tips.
How do you target veterans with ads if Meta restricts targeting?
Housing and financial ads on Meta run in a Special Ad Category with limited targeting options. We reach veterans through relevant creative, interest-neutral broad audiences, and organic channels such as veteran-focused community posts — not by excluding or including people based on protected traits.
Does the funnel mention the VA funding fee?
Yes, in the follow-up education, with a link to the VA's official funding fee page. We do not print fee percentages in ads; they change and depend on the borrower's situation.
Can a surviving spouse use the funnel?
Yes. "Surviving spouse" is an answer option, and the result page explains that some surviving spouses are eligible and that the LO can help check.
What if the borrower still owns a home bought with a VA loan?
The quiz asks. That answer flags "remaining entitlement" for the LO, because it changes the conversation. The result page tells the borrower it may still be possible to use the benefit and that the LO will check.
Is the copy respectful without being cheesy?
We avoid flags-and-fireworks clichés and generic "heroes" language. The tone is plain, grateful and practical, focused on timelines and paperwork that service members actually worry about.
No question matches that.
Try fewer words, pick "All", or send us the question — we answer within one business day.
Next stage: booked
Launch the va loan funnel in about two weeks
Book a call and we'll review your programs, traffic sources and compliance requirements, then send a written plan for this funnel.
Free 25-minute call · month-to-month plans · no ad spend required to start